Public Prosecutor warns seniors about risks of consigned loans
Public Prosecutor of Paraná warns seniors about consigned loans, financial scams, debt and pressure from family members

The ease of hiring consigned loans has caused concern with the indebtedness of retirees and pensioners. Despite generally lower interest rates compared to other credit modalities, monthly discounts directly on benefits can compromise the budget and make it difficult to pay essential expenses.
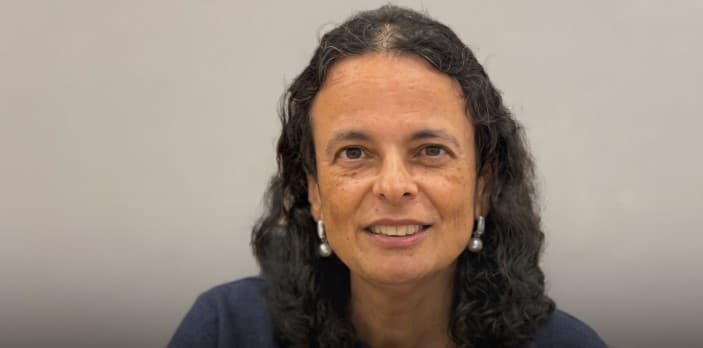
The warning was made by the prosecutor Elaine Lopo Rodrigues, of the Public Prosecutor's Office of Paraná (MPPR), during an interview with the MP program on Radio. The agency’s representative explained the main risks of contracting credit, the care needed before signing contracts and the measures that can be taken in situations of fraud or financial abuse.
Small plots can compromise the budget
According to the prosecutor, one of the main problems faced by the elderly is the difficulty of evaluating the impact of the parcels throughout the contract.
In many cases, the retiree considers only the amount that will be discounted monthly, without calculating the total amount of the debt or checking whether he will be able to keep the payment for several years.
As an example, Elaine cited the situation of a person who receives R$ 2,000 a month and assumes a benefit of R$ 500. Although the amount may seem manageable initially, reducing disposable income can compromise expenditures on food, medicines, and other basic needs.
The prosecutor also stressed that contracts with extended terms, such as those of 60 months, require financial planning. Even when the first installments are paid without difficulty, changes in family expenses can make debt a problem.
The total cost of the loan requires attention
Another point highlighted by the Public Prosecutor’s Office is the need to know the amount actually paid at the end of the financing.
Before contracting a consigned loan, the consumer should analyze not only the interest announced, but also tariffs, taxes and other charges involved in the operation.
The promoter presented as an example a loan of R$ 10 thousand, whose final value can be significantly higher than the amount received, depending on the conditions established in the contract.
She also explained that loans usually have lower rates because the payment is deducted directly from the pension benefit, offering greater guarantee to the financial institution.
Conventional personal loans usually have higher interest rates, precisely because they do not have the same discount mechanism.
Recordable margin sets limits for discounts
During the interview, Elaine explained how the recordable margin works, which determines the maximum percentage of benefit that can be committed to certain credit operations.
As presented by the promoter, the margin for INSS beneficiaries can reach 45%, distributed as follows:
35% for consigned loans;
5% for credit card deposit;
5% for consigned benefit card.
The division seeks to prevent retirees and pensioners from fully committing their incomes to financial debts.
However, the representative of MPPR pointed out that using all available margin does not necessarily mean that the hiring is financially secure.
Even within the legal limits, the discount can impair the maintenance of the consumer’s basic expenses.
Public Prosecutor Warns of Unauthorized Loans
The use of unauthorised loans was also discussed during the interview.
According to Elaine, there are situations where retirees identify discounts for operations they have not requested. In some cases, the amounts are deposited directly into the bank account; in others, the consumer perceives the discounts without even having received the money.
The prosecutor also warned of abusive commercial approaches over phone and messaging apps, especially when targeted at seniors.
She reported attending a retiree who began receiving loan proposals by WhatsApp shortly after the first payment of her pension benefit.
In the face of suspicious situations, the guidance is to initially seek the financial institution responsible to challenge the transaction.
If the problem is not solved, the consumer can register a complaint on the consumer.gov.br platform and seek assistance from the Public Defender's Office or the Public Prosecutor's Office, according to the circumstances.
Irregularities can also result in legal action and criminal liability, depending on the conduct identified.
Pressure from family members is also worrying.
In addition to the irregular practices of financial institutions, the Public Prosecutor’s Office draws attention to situations of property violence within the families themselves.
According to the prosecutor, there are records of elderly people pressured by children, nephews or other relatives to take out loans to serve the interests of others.
Situations can involve emotional blackmail, threats, and misuse of bank cards or passwords.
Elaine reported a case accompanied by the Prosecutor’s Office in which a family member committed about half of an elderly woman’s retirement. The situation was brought to justice, which ordered the annulment of the operation.
The representative of MPPR stressed that the elderly should not share passwords or give bank cards to others without proper care, even when it comes to close relatives.
When to look for the Public Prosecutor?
The Public Prosecutor may be sought in situations involving suspicion of fraud, coercion, financial abuse and compromise of the basic conditions of survival of the elderly person.
Among the cases reported are contracts made without the knowledge of the retiree, operations motivated by family pressure and discounts that leave the beneficiary without sufficient resources to acquire medicines or food.
The prosecutor also stressed that family members who identify these situations can seek guidance and communicate the facts to the competent bodies.
The main recommendation is that retirees and pensioners carefully evaluate any proposed credit before making long-term financial commitments.